

A community for all traders and investors. Technical, Macro, Micro Eyes Up Trading - Trade What’s in Front of You piped.video/c/TradersCommuni…
- Tweets 144,559
- Following 5,513
- Followers 21,732
- Likes 103,200


Pinned Tweet

Nothing broke — but everything got more expensive.
Fed tighter. BOJ tighter. Yen weaker. 10s at 5%. France/Bund stress widening. Oil near $100. Carry still alive. AI financing getting heavier.
The surface stayed calm. Underneath, the pressure kept building.
This week’s Cautious Investor:
traderscommunity.com/cautiou… #Macro #CarryTrade #Bonds #Oil #Markets

Made with AI
4
4
8
1,572
Meaningful deterioration in the negotiation picture:
A senior Iranian official told Reuters on Friday, September 25 that Iran will make “no flexibility” on its nuclear program even if Washington accepts Tehran’s proposal for reopening the Strait of Hormuz.
More importantly for crude, the official said Hormuz will remain closed until all Iranian conditions are met. #MoreOfTheSame #OOTT
542
Traders Community retweeted

France’s Economy Is Losing the Confidence Game
Soaring fuel prices and limited options for governmental help are driving French households into crisis mode. bloomberg.com/news/newslette…
1
5
38
26,613
Traders Community retweeted
#Italy's Eni caps fuel prices as Meloni struggles to tame rising costs #oott reuters.com/business/energy/…
1
2
3,049
Meaningful #Oil physical-flow development:
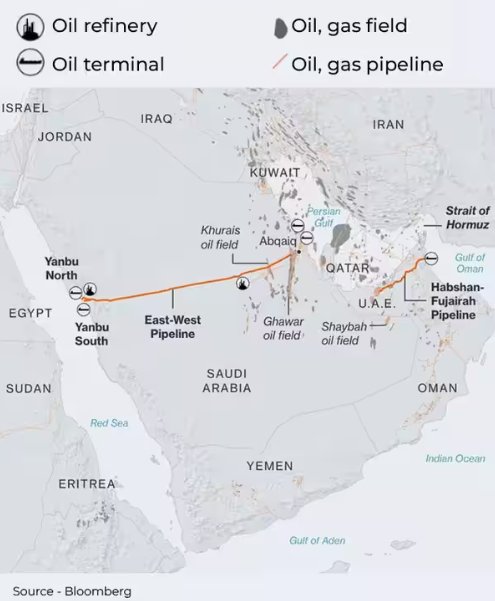
The workaround keeping Gulf crude moving is now hitting a capacity constraint.
Reuters reports that ship-to-ship transfers in the Gulf of Oman have reached their practical limit as Saudi Arabia reroutes exports back through the Strait of Hormuz following the attack that halted Yanbu exports. #OOTT
2
2
5
1,209
Combined Gulf STS volumes are running around 6 million bpd, but congestion has doubled the time required for a transfer to roughly 10 days.
VLCC charter rates to China consequently reached a record $1.27 million per day this week. Buyers are now seeking alternative transfer locations off India and Malaysia.
1
139
Traders Community retweeted

So by “technical phase” it seems they mean the technicalities for how talks might be held, not the technicalities of a potential agreement.

Qatar says talks were held with Iran on conditions for "dialogue" cbsnews.com/live-updates/ira…
1
5
18
2,896
Traders Community retweeted
Sanctions must be liftef to end diesel export ban - Kremlin
Tass #oott
2
13
7,091
Brent–WTI spread is now the widest since May, with Gulf supply problems keeping the Brent premium elevated. Brent–WTI an enormous $12.55.
Look underneath crude:
Gasoline −3.4% / WTI −2.4% / Heating Oil only −0.5%.
So don't read this as simply “energy inflation problem solved.”
The barrel is repricing, but the distillate problem is still sitting there.
Gasoline is taking the beating while HO refuses to follow crude proportionately. That keeps your crack-spread/refined-product theme very much alive. #OOTT

Crude lower after yesterdays double top,
#Natgas down sharply
WTI 92.326 2.284 -2.41%
Brent 104.880 1.72 -1.61%
Gasoline 3.4429 0.1217-3.41%
Heating Oil 4.7060 0.0243-0.51%
Natural gas 3.1495 0.1475 -4.47%
$UCO $SCO $XLE

3
563
An interesting framework:
Equities: AI demand is enormous.
Corporate credit: Fine, but who finances all of it, at what spread, and how much more paper is coming?
Project finance: Will the power/data-center projects arrive on time and on budget?
Capital cycle: And what happens to returns if everybody builds at once?
That is considerably more consequential than merely saying “AI bubble.”

2
404
P&D reminder more bonds hitting the street means existing paper has to reprice sufficiently to clear that supply.
That's a classic capital-markets pressure independent of whether AI revenues eventually justify the investment.
1
441
Market starting to price risk:
AI Hyperscaler CDS spreads blowing out as Oracle hit record high
$ORCL 5year Credit default swap rose 16.2% on the week across both bid and ask quotes, reaching a record 227.15 bps.
Recap: Oracle issued a force majeure notice to developer of its massive “Project Jupiter” data center in New Mexico as it stretches itself with the paramount Discovery deal.
Other major tech & hyperscaler CDS widening include Google $GOOG $GOOGL Microsoft $MSFT Amazon $AMZN Meta $META Nvidia $NVDA SpaceX $SPCX

1
3
5
613
BofA right on top of things
Downgrades Nike to Underperform, cuts PT to $30 after falls over 50% - nice work
NIKE, Inc. $NKE 35.22 -0.79 (-2.19%) Premarket
52 Week Range 35.35 - 76.97
- saying the company’s turnaround is taking longer to materialize as weakness in its larger lifestyle categories overshadows product innovation.

1
2
511
Gold higher with US dollar slightly weaker as yields take a breather
#Gold 4303.89 29.24 +0.68%
#Silver 64.791 0.969 +1.52%
Copper 6.6966 0.0219 -0.33%
JPY leads & CHF lags i.e #CHFJPY carry
#USDJPY - 0.75% EURUSD up 0.2% AUDUSD up 0.3% to 0.7030.
Japan finance minister Katayama saying principles behind July’s joint intervention remain in place.
Japan prime minister Takaichi reveals that US president Trump had told her that a weaker yen is putting pressure on US trade.

1
1
1
515