

Bitcoin and Digital Credit | Advisor, Moirai Capital and @saturn_credit | Stanford
New York
- Tweets 16,002
- Following 462
- Followers 17,441
- Likes 28,658


Pinned Tweet

Look, the strategy is really simple. Keep DCA-ing into #Bitcoin. That's it. Seriously, you can stop reading here.
39
73
585
147,109
Brian Brookshire retweeted

BTC consolidating here. more coins have moved onchain in the $83.6k - $84.8k range than any other price band 👀

11
14
133
9,149
Bitcoin feels like it wants to close the weekly below the May high to keep breakout traders on their toes.
1
14
1,304
YES. Daily dividends that also accrue on weekends and holidays for Strategy prefs.


4
9
206
5,059

Brian Brookshire retweeted

$STRN
TGE: Q4 2026.
There is no second best.
Initial details below.

96
61
440
112,095


Brian Brookshire retweeted

$MSTR $ASST A lot of people have asked me: why should a Bitcoin treasury company trade above 1x mNAV?
There are four reinforcing mechanisms that expands mNAV:
1. Credit creates BTC/share growth
A treasury company can issue debt, converts, preferreds, and other forms of credit to acquire more BTC without issuing common equity.
If the cost of that capital is below the long-term appreciation of Bitcoin, the company captures the spread between BTC CAGR and its cost of capital.
That creates organic BTC/share accretion.
So mNAV is not necessarily just a valuation of today’s NAV. A premium can reflect the market’s expectation that BTC per share will continue increasing over time.
2. Leverage creates volatility, which makes the premium more reflexive
The same credit that increases BTC/share also introduces leverage into the equity.
As a result, the stock becomes a higher-beta exposure to Bitcoin and can overshoot movements in underlying NAV.
Once the stock trades at a premium to NAV, that premium itself becomes a source of financing.
The company can issue common stock above NAV, use the proceeds to acquire more BTC, and further increase BTC per share.
This creates a powerful loop:
Credit → BTC/share growth → mNAV premium → common equity issuance → more BTC/share growth
3. Options liquidity magnifies the volatility
As liquidity builds around the company’s options chain, the volatility created by balance sheet leverage can be amplified.
More options activity creates additional positioning and dealer hedging flows in the underlying equity. These flows can be relatively price-insensitive, and can add buying or selling pressure on either side of the market.
The options market therefore acts as an amplifier on top of the volatility created by leverage, which can further expand the mNAV premium and increase the accretive potential of common equity issuance.
4. Scale creates structural demand
As the company raises capital and acquires more BTC, it can eventually enter larger indexes, creating further non-discretionary buying that is not directly tied to BTC price movements.
That creates another feedback loop:
More capital → more BTC → larger market cap → index inclusion/passive demand → higher equity value → higher mNAV → more capital
These mechanisms reinforce one another.
The market isn’t just valuing the BTC a company owns today. It’s pricing the company’s ability to grow BTC per share over time.
The key is that the mNAV premium is not just an output of this flywheel. Once it exists, it becomes an input into the flywheel itself.
1
2
25
1,680

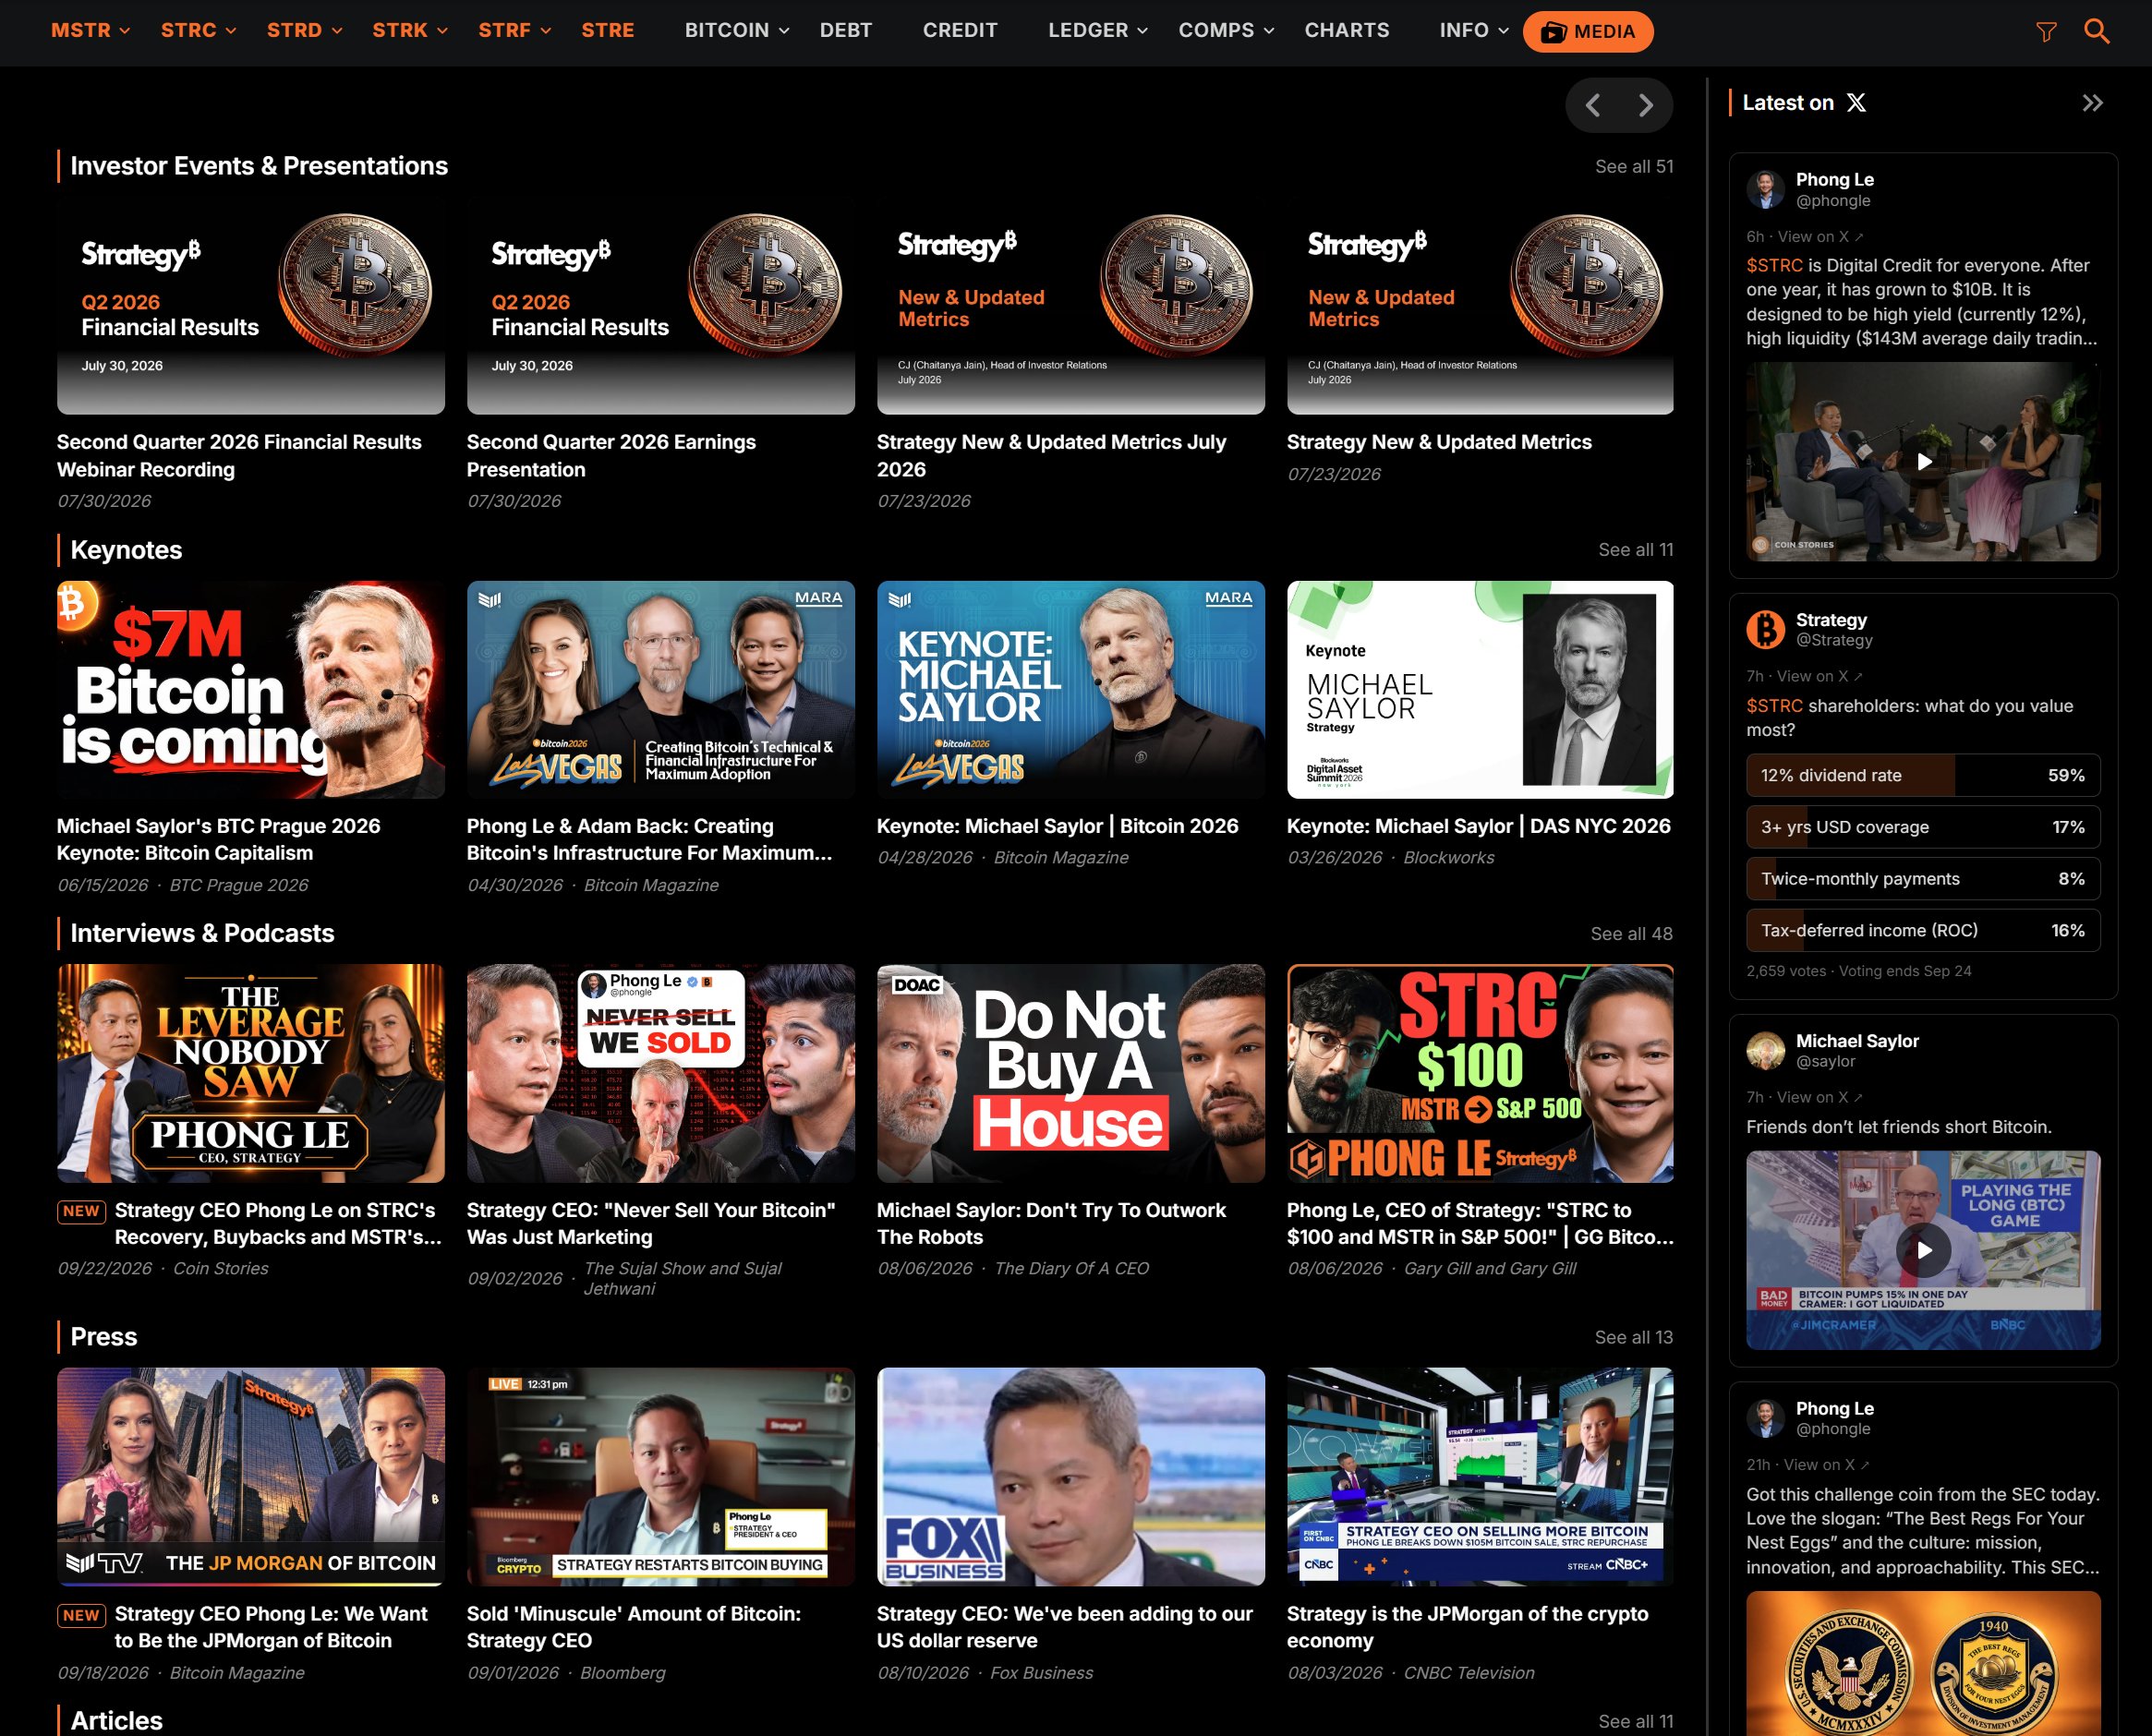
We brought X to Strategy.com.
The Media tab now features a live feed of the latest Strategy posts, alongside our latest Presentations, Keynotes, Interviews, and more.
48
82
1,091
76,680
I like that BTCTC management compensation continues to be a topic of conversation and hope to see continued transparency and reform across the industry.
What we saw in 2024-25 was an explosion of companies from different industries, different backgrounds, and different levels of sophistication pivot to a Bitcoin Treasury model.
Bitcoin Treasuries are somewhat unique in that the stock itself is the product.
More so than in any other type of business, management compensation is a hurdle rate to share performance that needs to be aligned with shareholders, competitive with peers, and clear to analysts.

A FIRST PRINCIPLES FRAMEWORK FOR MANAGEMENT COMPENSATION AT BITCOIN TREASURY COMPANIES (LONG READ)
There has been a lot of discussion recently around executive compensation, management ownership, founder ownership, dilution, and incentives across digital asset treasury companies. It is healthy that investors are digging deep here. Trust is critical to the long-term success of this industry and foundational to the operating model Strive has built. It is part of why we publish The Hurdle Rate every week. Shareholders should have a regular window into how management thinks, how we make decisions, and how we approach difficult questions. As this conversation develops, the best place to start is with first principles and make sure we are measuring the things that actually matter.
Compensation philosophy has three primary purposes: recruit the best people, retain the best people, and incentivize them to create value for shareholders. The amount has to make sense for the size, complexity, opportunity, responsibilities, and performance of the company. Set it too low and you will likely fail to recruit or retain exceptionally talented people. Set the incentives poorly and even a modest package can drive the wrong behavior. The way management earns its compensation is critical. The goal needs to be a meaningful carrot for exceptionally talented people, with incentives that make management more successful when shareholders are more successful.
Strive comes at this conversation from an unusually beneficial starting point. Corporate governance was why Strive existed as an asset management company in the first place. We were founded around a belief in shareholder primacy, meaning the shareholder is the most important stakeholder. Period. Employees, customers, communities, and other stakeholders obviously matter, but when interests conflict, management has to know whose capital it is stewarding and whose interests come first. Most of the asset management industry had moved toward stakeholder capitalism, where shareholders, employees, customers, governments, and other constituencies were increasingly treated as co-equal. Our view from day one was that you cannot serve multiple masters equally when their interests diverge.
That principle shaped the way we approached corporate governance from the beginning. We focused on whether boards and management teams were acting in shareholders' interests, whether executive incentives were aligned, whether fiduciaries were staying within their mandates, and whether ESG, DEI, and other considerations were introducing incentives that could conflict with shareholder value. Management incentives and executive pay were therefore already embedded in Strive's DNA long before we became a Bitcoin treasury company. Applying that same framework to the Bitcoin treasury landscape is natural for us. When shareholders look under the hood at Strive, they find both transparency and a compensation framework designed from day one around shareholder alignment.
Our own compensation program was built within that same framework. Under our Board's direction, we used an independent compensation consultant to develop it and initially benchmarked overall compensation around the 50th percentile for comparable roles. At the time, our Bitcoin strategy was new and we had not yet built a performance record. The 50th percentile was a starting point, not a permanent ceiling or floor. As the company grows, responsibilities increase, and a performance record develops, the Board will continue assessing where compensation belongs using the same disciplined framework. Sustained exceptional performance would likely increase the amount of compensation that could be earned, just as sustained underperformance would likely move it in the other direction.
That background is also why I disagree with an important part of VanEck's recent analysis of digital asset treasury compensation:
vaneck.com/us/en/blogs/digit…
VanEck deserves credit for bringing more attention to the issue and highlighting legitimate governance concerns. But one of the key parts of its framework put too much weight on the relatively simple question of whether executive awards had a performance hurdle. That analysis does not go nearly far enough for a balance sheet company, and it produces a set of conclusions I fundamentally disagree with. BitMine, for example, ranked near the top of their analysis. That makes it a useful example to examine more closely, particularly because it is an Ethereum treasury company and avoids turning this into a direct comparison with one of Strive's Bitcoin treasury peers.
BitMine's disclosed hurdles include stock price, market capitalization, and reaching specified percentages of total ETH supply. All three are measurable. The problem is what those measurements incentivize. If ETH appreciates substantially, the stock can appreciate even if shareholders would have been better off simply owning ETH. Market capitalization can rise through additional share issuance. Reaching a larger percentage of total ETH supply encourages accumulating more ETH, which can also be facilitated through issuing additional equity. Management can therefore meet the goals of those incentives by increasing the absolute size of the company without necessarily creating superior value for each share outstanding relative to Ethereum. I view that performance structure as inappropriate for a balance sheet company because it introduces meaningful potential for misalignment with shareholders.
A balance sheet company built around a primary asset should have to outperform that asset, full stop, for the biggest management paydays to occur. Otherwise, management can be rewarded substantially while shareholders would have been better off simply buying the asset.
Strive provides a useful contrast. If Bitcoin rose 300% and Strive rose 200%, we would have underperformed Bitcoin. The most important component of our long-term incentive framework would therefore not have been satisfied. If we were underperforming Bitcoin, it would also be very unlikely that we were simultaneously generating a strong positive Bitcoin Yield, which would put pressure on our short-term incentives as well. You can quickly see why the design of a performance test is critical. We do not want the majority of management incentives earned simply because Bitcoin appreciated, the company became larger, or we issued more shares and bought more Bitcoin.
Our short-term and long-term incentives are designed to answer different questions over different time horizons. Short-term incentives focus on Bitcoin Yield because a well-run Bitcoin treasury company can reasonably underperform Bitcoin during an individual year while still making accretive decisions that improve Bitcoin exposure per share. Our long-term relative performance framework is measured over three years, which gives management enough time to demonstrate whether those decisions actually produced superior shareholder outcomes versus Bitcoin. That combination keeps management focused on per-share value creation in the near term while preserving Bitcoin as the long-term hurdle rate.
Strive's early scoreboard is encouraging. As of the September 21, 2026 close, Strive has outperformed Bitcoin by more than 100% year to date. Since we announced our Bitcoin treasury strategy in May 2025, Strive has outperformed Bitcoin by approximately 157%. Our long-term incentives are measured over three years, so roughly sixteen months is still an interim result and it is important to zoom out. But both year to date and since the strategy's inception, Strive has delivered substantial outperformance versus Bitcoin. Ultimately, company performance matters most. Shareholders would rather own a company producing exceptional results with an imperfect compensation framework than one with a theoretically perfect framework that fails to perform. Incentives matter because over time they shape behavior, and better incentives should increase the probability that strong performance is sustained.
It is also important that investors separate backward-looking and forward-looking analysis. Looking backward is largely about trust. Was the company transparent? Was management accessible and willing to answer difficult questions publicly? Did management treat shareholders fairly? Did insiders compensate themselves responsibly? Did management do what it said it would do? Has management earned investors' trust through its historical actions? Looking forward, investors should start with the talent of the people actually running the company today, then ask how much they can earn, how they earn it, what behavior those incentives encourage, and whether management creates more value for itself by creating more value for shareholders.
Founder ownership established when a company was founded belongs in that historical analysis. At Strive, that distinction is particularly important because Vivek founded the company but is no longer part of Strive's management team. His ownership is legacy founder ownership, not compensation being paid for managing the public company today. A founder creates a company, begins with an ownership position, and then makes decisions over time about raising capital and dilution. Once outside shareholders are invested, ongoing management compensation should be evaluated based on the work being done today and the value being created going forward. If a founder diluted themselves, that dilution is not a debt owed by future shareholders simply because they still carry the title of founder. Using a legacy founder stake as a benchmark for what current management should be paid obscures compensation analysis. Neither founders nor employees are entitled to anything. Compensation always has to be earned.
When investors evaluate management compensation at any treasury company, they should look at the full framework. Is the package sufficient to recruit and retain exceptionally talented people? Does the amount make sense for the scale, complexity, opportunity, responsibilities, and performance of the company? What does management actually have to accomplish to earn it? Can management earn more simply by increasing the size of the company, or must it create value on a per-share basis? Does management have to outperform the underlying asset for the largest awards? Can dilution make targets easier to reach? How transparent is the company about the framework and its historical results? No framework will ever be perfect, but those questions establish a useful standard for assessing whether incentives are likely to serve shareholders.
That is where investors should push the industry conversation to go. The size of an award matters. Performance conditions matter. Serious governance analysis also has to get underneath those headline numbers and understand the economic incentives management is actually responding to. At the end of the day, company performance is the scoreboard. The purpose of compensation philosophy is to recruit and retain the people capable of producing exceptional results and align their incentives so that the path to exceptional compensation runs through exceptional outcomes for shareholders.
I have written quite a bit about this already. For anyone who wants the underlying data and complete context, I would recommend reading these together. You can also put them into whatever AI system you use and conduct your own analysis with the full information:
1. Strive's compensation philosophy and forward-looking incentive framework
- My original deep dive into how Strive thinks about management compensation, including benchmarking, Bitcoin Yield, relative performance, and the philosophy behind the program.
nitter.net/ColeMacro/status/20951…
2. A framework for evaluating Bitcoin treasury company compensation
- A broader framework for separating backward-looking trust from forward-looking incentives and evaluating both how much management can earn and how it earns it.
nitter.net/ColeMacro/status/21023…
3. Forward-looking compensation deep dive
- Additional detail on Strive's current incentive framework, performance metrics, and how management earns compensation going forward.
nitter.net/ColeMacro/status/21009…
4. Backward-looking compensation deep dive
- What Strive management has actually been paid historically and the context necessary to evaluate that record.
nitter.net/ColeMacro/status/21009…
5. Founder ownership versus current management compensation
- Why founder equity established at formation, merger consideration, and compensation paid to today's management team need to be evaluated separately.
nitter.net/ColeMacro/status/20974…
6. Additional context on legacy founder ownership
- Why a legacy founder position reflects the company's formation and financing history rather than a benchmark for what current management should earn.
nitter.net/ColeMacro/status/21023…
7. Neither founders nor employees are entitled to equity
- Why compensation has to be earned and why dilution previously accepted by a founder is not an obligation future shareholders have to repay.
nitter.net/ColeMacro/status/21024…
Shareholders should dig deep, ask hard questions, understand the incentives, and then watch the scoreboard. That combination of transparency, alignment, and performance is how this industry earns durable trust.
5
3
55
4,538
Brian Brookshire retweeted

BREAKING: We just caught another interesting trade.
President Trump just filed multiple July purchases of Microstrategy stock.
$MSTR has risen 83% since his purchase on July 24th.


160
413
4,257
622,062
Some people told you $MSTR was in a death spiral and unable to pay its dividends.
Some people co-authored books giving you the correct answer that "yes" it can pay its dividends.
Choose your follows wisely.

3
2
43
2,052
There is still a lot of skepticism about bitcoin having entered a new bull cycle. Personally I think the bull has started.
At some point there will be a significant correction. My guess is from higher. If history is any guide, every dip for the next 2-3 years is an opportunity.
1
3
38
2,112


Yikes. A BTCTC below 1x mNAV is often a bargain, but this is not one of those times $DDC.

The Other Side of Every Trade: DDC
$DDC trades at a $12.7M market cap against $251M of bitcoin (2,899 BTC). 0.05x.
I've spent some time looking at the details and working out why. What's happening:
• A July 2025 convertible that converts at 94% of the lowest close of the prior ten days, no floor, first lien on the bitcoin. ~$17M is still outstanding. At Monday's price that's 83M new shares against 59M in issue. The holder converts, sells, waits for the low to reset, converts again.
• The share count went 8.3M → 56.8M in thirteen months. The bitcoin went 3.3x. Bitcoin per share is down 43%.
• Stock down 66% since an H1 print that cut liabilities by $50M. On Monday bitcoin rose 6.6% and DDC fell 9.6% on 72M shares. The balance sheet improves and the equity doesn't notice, because it isn't the equity's balance sheet anymore.
Management's side of the table:
• 875,000 Class B shares issued to the CEO at par for $14,000, eight weeks after the note. Vote raised from 10 to 100 a share. 75.5% of the vote for less than a used car.
• A warrant pool that resets every year to 25% of the count, strike at the board's discretion. Grants struck at $0.16 while the stock was at $10.
• A second evergreen registered in August. A $10M buyback with zero shares bought.
• Norma Chu ran equity research at HSBC before this. The three independent directors are the entire audit, compensation and nominating committees. They approved all of it!
They either didn't understand what they signed in the summer of 2025, or they understood it and built themselves a position the terms can't reach. Both are bad and disqualify the equity for a minority holder.
Subscribe to the Pharaoh Brief for the full piece: thepharaohbrief.substack.com…
$DDC $BTC
2
1
40
8,138
Brian Brookshire retweeted

Just a reminder that every single pleb who has been dollar cost averaging bitcoin is now in profit no matter when they first started DCA'ing. Every single one of them!


Just a reminder that every single pleb who has been dollar cost averaging #bitcoin is now in profit no matter when they first started DCA'ing. Every single one of them!

56
203
1,363
212,721
Another way to monitor market changes in the BTCTC landscape is to keep track of sentiment toward management teams.

Made with AI
8
4
34
3,132
Things that will happen again this bitcoin cycle:
- mNAVs will expand into blow off tops.
- A new cohort of top blasters who bought the blow off top will complain endlessly until the next bitcoin cycle highs.
- People will once again act as if this has never happened before.
8
4
125
3,603