

Looking through the stories markets tell themselves. Macro, Tech, Geopolitics. Founder: DeFi Advisors. Investor, Writer @ substack.com/@mnicoletos
London, England
- Tweets 29,902
- Following 5,746
- Followers 73,780
- Likes 48,948


Pinned Tweet

We tend to treat these as separate stories. Bitcoin. Stablecoins. Tokenization. AI. AI agents.
Look at them together and a different picture appears.
The dollar is already onchain. More than $300 billion of stablecoins moved $11 trillion last year, and stocks, bonds and funds are starting to follow.
At the same time, AI agents are learning to do work on their own. They will need to pay for things at any hour, often in amounts too small for a card. Money that moves like software is built for exactly that.
Seventeen years of building the pieces without the picture on the box. I think they are starting to fit.
Link:michaelnicoletos.substack.co…
#AI #AIagents #Blockchain #Tokenization #Stablecoins #RWA #USD #Banking #Payments #Bitcoin

Made with AI
25
2,131
2,206
195,415

SECRETARY RUBIO: For twenty-five centuries since, the Parthenon has stood. Empires have risen and fallen beneath its shadow.
And the progeny of the men who built it – the sons of Athens and Rome – have carried their civilization with them to the ends of the Earth.
Two and a half centuries after the founding of the American republic halfway across the world from where I stand now, I stand here today – as the Secretary of State of that republic, and as the great-grandson of settlers who arrived in the new world from Spain – I stand here to testify to a debt that no lapse of time, no distance of space, can ever extinguish.

6
112
416
40,107
Life is funny sometimes!
For those who don’t know. This is the back of Brent’s @SantiagoAuFund business card.
@LukeGromen

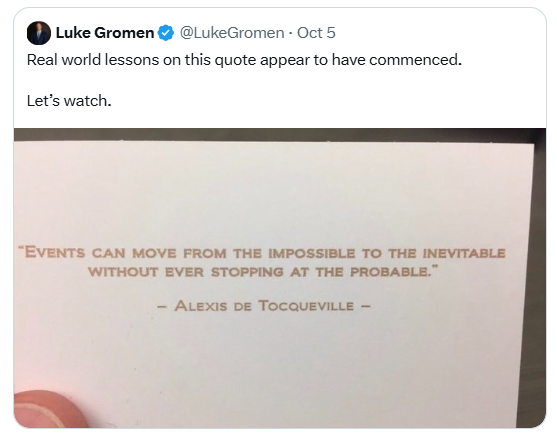
1
2
14
2,190
Michael Nicoletos retweeted

I absolutely love The Economist: The US is has caved to China with a 35% tariff but Europe is amazing because two presidents sent a letter saying we should do something. Their brilliance is always a wonder to behold

An astonishing joint letter suggests confrontation looms with China economist.com/europe/2026/10…
12
49
489
12,516
If the US 10y suddenly moves higher and triggers a short squeeze (given the short position in the US 10y this is not unlikely) the short squeeze in the Russell 2000 will be even more monumental.

Short interest (as % of shares outstanding) in the Russell 2000 has risen to the 99.8th percentile.
JPMorgna via @BlakeMillardCFA

1
3
1,942
For how long will the #ECB focus on its Green Bonds and sustainability initiatives before it starts addressing the issues it should be addressing? These initiatives have only exacerbated the problem and made access to capital more expensive.
The ECB needs to realize that it needs to cut rates asap an address sovereign liquidity issues.
#QE or Yield Curve Control (#YCC) is just around the corner.
#France #Euro

Most people don’t yet grasp what is happening in France. Markets are pricing French sovereign debt as junk, rating agencies will eventually have to follow. This will have two major impacts:
1. Most French banks are already rated at or just below the sovereign, so a move toward junk would likely drag domestically focused lenders with it. Credit to households and firms would slow sharply, hurting the economy and widening the fiscal deficit even further, a vicious cycle.
2. For the ECB, the constraint is legal as well as financial. A fall below investment grade would force sales by ratings-bound investors while making any backstop harder to justify under current rules.
The next euro crisis will begin in France. The first, which began in Greece, will feel like a walk in the park compared with what comes next.

1
12
1,986
I agree with this post. I thought the squeeze on the US 10y would have come earlier (below 5%). I was wrong on the timing. In any case when this move occurs (which I expect it to be soon) in the US 10y it will be one for the books. I would not want to be short. Buying more calls.

This Is Not Your Grandfather’s Treasury Market.
Hedge funds are now dominant players in the 10-year futures market, and their short is one of the largest on record. Bessent knows this.
As of the September 29, 2026 report, leveraged funds were short 2.04 million contracts, about 36 percent of the market. The peak was 2.53 million contracts, roughly 45 percent of open interest, on August 26, 2025. The position has eased since then. It has not returned to normal.
History makes the scale clear. Before 2023 this short rarely rose above 1 million contracts. In the 2008 crisis it reached only about 10 percent of the market. In the 2022 bond selloff it reached about 18 percent. From 2006 through 2021 it often switched between long and short and stayed far below today’s level.
The old Treasury market was shaped mainly by banks, dealers, and long-term investors. The buildup that began in 2022 put hedge funds at the center: a larger and more persistent short than in prior cycles. That is concentrated exposure in the benchmark rate that prices mortgages, corporate debt, and government borrowing.
Is this why the bond vigilantes are ignoring the data? A short this large does not need a fresh inflation print to keep yields high. It just needs the Fed to continue with its old flawed playbook.
Now you can see why data that shows inflation declining is ignored and questioned.
The position is already on, and a softer print is a threat to it. The other side is the unwind. If that crowd has to cover at once, a squeeze of historic proportions could follow, a rush to buy back a position bigger than anything seen in 2008 or 2022.

3
6
112
28,590
Anyone want to discuss the US Treasury market?

France collapses. The biggest public sector in developed economies, massive regulation, uncontrolled immigration, and the highest taxes in the OECD. Asphyxiating the private sector in a country with high human and entrepreneur capital.
What could go wrong?
Result. Vandalism, discontent, stagnation, and a massive debt crisis
bloomberg.com/news/articles/…

2
5
36
2,455
#China says its economy grew 4.7% in the first half of 2026.
Now look at what that growth is supposed to stand on.
• Fixed asset investment: down 7.2% through August, about $335 billion less than a year earlier.
• Property investment: down 19.9%.
• Construction output: down 4.1% in Q2.
• New orders at the big state builders: falling. China Railway Construction was down 17% in H1.
Investment is around 40% of China's GDP. When 40% of an economy shrinks by 7%, you need almost 3 points of growth from somewhere else just to stay flat.
Consumers are not filling the gap. Retail sales of goods rose just 1.1%.
Exports did the heavy lifting, up 13.4%, and delivered about a fifth of Q2 growth. But imports rose even faster, up 22.1%, so the trade surplus actually shrank.
And yet the official accounts say investment added about 1.5 points to growth in H1. The monthly data say investment shrank. The GDP accounts say it grew. Same economy, same six months, two opposite stories.
The Bank of Finland's model puts Q2 growth at 3.1%, not 4.3%. The official figure sits near the very top of its range.
Q3 GDP comes out October 19. Watch how neatly it lands.
Why the world keeps looking away 👇
michaelnicoletos.substack.co…

20
158
502
48,157
Michael Nicoletos retweeted

#Greece: RSF warns about the growing intrusion of Beijing’s propaganda. Having developed its presence in the mainstream media landscape, #China is now turning its attention to 🇬🇷 social media. By cultivating a network of influencers, the 🇨🇳 regime is spreading its narratives to a broad audience who are often unaware of their ties to the Chinese state.
rsf.org/en/china-s-quiet-inf…

22
71
144
13,507
Michael Nicoletos retweeted

In the @ftopinion article below, @martinwolf_ claims that the average maturity of US Treasury issuance decreased from 6.1 years in 2024 to 2.5 years in 2026. He should check his math. The 2024 figure appears to entirely exclude bill issuance in that year, whereas bill issuance is fully included for 2026. In effect, he is comparing apples to broccoli.
The truth is that the WAM of all outstanding debt has barely changed between 2024 and today (5.9 vs 5.8 years). The Treasury regularly publishes a wide range of portfolio metrics in order to provide market participants with an accurate picture of the debt maturity structure. @FT writers should consult these data before publishing claims that mislead its readers.

40
48
433
162,819
The chart is the symptom. The disease is the policy response.
An energy shortage is not an overheating economy. It is a supply shock, and it already works as a tax on every household and every factory. Higher rates cure demand. They do not create gas, diesel, or baseload. Draining liquidity on top of that tax does not stabilize anything. It deepens the hole.
Europe spent years retiring the system that kept the lights on, then treated the bill as a communications problem. The Commission and the ECB have lost contact with what people actually pay. Leadership is still on the bridge, insisting the ship cannot sink.
The next elections will not be about the narrative. Hungry people do not vote for pipe dreams.
Most people don’t yet grasp what is happening in France. Markets are pricing French sovereign debt as junk, rating agencies will eventually have to follow. This will have two major impacts:
1. Most French banks are already rated at or just below the sovereign, so a move toward junk would likely drag domestically focused lenders with it. Credit to households and firms would slow sharply, hurting the economy and widening the fiscal deficit even further, a vicious cycle.
2. For the ECB, the constraint is legal as well as financial. A fall below investment grade would force sales by ratings-bound investors while making any backstop harder to justify under current rules.
The next euro crisis will begin in France. The first, which began in Greece, will feel like a walk in the park compared with what comes next.
4
198
273
25,172
Michael Nicoletos retweeted

Im no Oracle, but I suspect Le Pen will win the next election by a massive majority.

768
3,110
33,131
656,642


The Senate failed to advance America’s crypto rulebook 49–50. It needed 60.
Two days later the SEC opened a conditional path for real U.S. stocks, dividends and votes included, to trade on blockchains. A week after that, the futures regulator said brokers may invest client funds in tokenized Treasuries.
Next month, the depository that holds $114 trillion of U.S. securities launches its tokenization service.
Congress stalled. The plumbing did not.
michaelnicoletos.substack.co…
#ClarityAct #SEC #CFTC #Tokenization #Trading #Blockchain #Bitcoin #Stablecoins

Made with AI
7
5
587
52,012

David Sacks compares banning AI to the Chinese emperor who banned shipbuilding
“If you go back to the medieval time period, Chinese civilization was much more advanced than European civilization. And somewhere along the line, it basically switched and the West basically took the lead. And some historians have pinpointed this to the decision of a single Chinese emperor to ban shipbuilding."
“What that allowed is the Europeans then basically colonized the whole world and all the riches that flowed from that flowed back to Europe. And that's how Europe took the lead. And I think that if we were to do the Bernie Sanders thing, which is basically ban AI, it's like banning shipbuilding."
“Chinese civilization will rocket past us, they will be the ones that make all the discoveries and discover this new world and accrue all the wealth. But that's what we're talking about doing. I mean, crazy things like this have happened in history, where you'll engage in self sabotage."

57
269
1,525
95,090
Michael Nicoletos retweeted

I just spent the last two hours in a deep-dive conversation with Logan Wright, who has written what I think is the most insightful and provocative book on China's economy written to date.
Logan essentially argues that the world’s largest economy by purchasing power parity is in structural decline, its currency is overvalued, and its party leadership—contrary to conventional wisdom—is not imbued with the long-term strategic foresight so often attributed to it.
The episode publishes Monday, and while I read every page of this book and we did the very best we could to help both distill and expand on the insights and arguments that Logan puts forward, I still recommend pre-ordering a copy, as there is no substitute for reading it.

48
42
296
45,513
Michael Nicoletos retweeted

.@larry_kudlow in @NewYorkSun gets it right. Here are the facts:
The dollar was on one side of 89.2% of global FX trades.
Foreign investors still hold enormous amounts of U.S. assets. The principal stablecoins are dollar-denominated. Treasury buybacks are about adding liquidity and managing the maturity structure, not somehow controlling a $30T+ market.
Median household income in 2025: $87,460 — a record.
Official poverty rate: 10.2% — a historic low.
Atlanta Fed GDP forecast: 5.1% annualized real GDP growth in Q3.
And that’s before looking under the hood at the private-sector momentum behind capex and the AI buildout.
The latest numbers show continued employment growth, while business investment and capital expenditures have been expanding, as the CapEx comeback story has continued to broaden out, with nearly 20% more equipment investment in Q2 2026 than at the end of Biden’s term.
Americans deserve honest coverage.
In the New York Times’s latest feeble attempt at delivering a hit piece on the greatest economy in history, the discredited journal selectively excludes data that contradicts this dull narrative. Granted, it’s nothing new that they fail to provide their readers with the full story.
Complicated financial realities should not be reduced to easy-to-read sentences that serve a preordained narrative.
This article’s problem is not complexity. It is selectivity.
If capital is supposedly running from America, why does the data keep showing strong foreign demand for U.S. assets?
If investors are “balking” at Treasuries, someone forgot to tell the bidders.
Norway is not looking elsewhere; it is switching from Treasuries to agency bonds. Still US assets.
Netherlands is bringing gold back from North America, including Ottawa as well as New York, reflecting a home country preference.
We see this morning that Saudi Arabia has dropped out of mBridge and others are likely to follow.
And if digital finance is supposed to threaten the dollar, why are stablecoins overwhelmingly dollar-denominated?
The record is not ambiguous.
nysun.com/article/the-new-yo…
427
2,405
8,900
294,487
Who would have thought? 🤔
Saudi Arabia has withdrawn from a Beijing-led digital currency programme that is part of #China’s efforts to develop an alternative cross-border payments system to the #dollar.

Saudi Arabia quits China-led cross-border currency platform ft.trib.al/NV8faWl
Community note
Saudi Arabia's central bank SAMA completed its mBridge proof of concept on May 13 2025 and ended participation as originally planned; it has not been a participant since.
business-standard.com/world-news/sau…
moneycontrol.com/world/saudi-ar…
cryptobriefing.com/saudi-arabia-w…
14
7
49
8,597