

Serving professional money managers. Tweets are an exchange of ideas not investment advice. Life is short, if you're a jerk, you'll be unceremoniously blocked.
New York, NY
- Tweets 9,970
- Following 1,110
- Followers 63,203
- Likes 27,657


Relative Strength: Russell 1000 Insights & Analysis
Catch the full episode here: piped.video/f2EVDf1bP44
Hawk and Awe: RenMac Off-Script
#MarketAnalysis #Investing

1
3
3,359
Treasury Yields Hit Highest Level Since Before Financial Crisis
Get the story on the RenMac Pod: piped.video/f2EVDf1bP44
Hawk and Awe: RenMac Off-Script
#Yields #Markets #Economy

3
2
4
4,208
Fed Rate Hike Rationale
Get the full story on the RenMac Pod: piped.video/f2EVDf1bP44
Hawk and Awe: RenMac Off-Script
#InterestRates #Economy #Finance

1
2
10
4,714
Durable goods shipments remain quite strong, but it is worth noting that key components (especially primary and fabricated metals) are largely a price story. One way to read the figure: below the line implies contraction in real terms and above the line implies the opposite.

3
5
26
4,959
An update to our $SPCX vs other marquee IPOs over the last 30-yrs. We called it a hype tax in June, and the market collected it. History suggests better opportunities around beginning of year.

4
1
36
5,135
Anecdotes aren’t a substitute for hard data but this follows news from Disney raising subscription prices. The bigger issue is that it’s all happening with core inflation already well above the Fed’s target.


3
6
30
11,359
Supply chains are screwed up, but probably not as screwed up as they were a few years ago, which implies that there is less room for improvement in supply chains to bring price relief. This means we'll need to rely more on demand to get inflation consistent with price stability.

2
7
40
5,516
Oil prices coming off the boil has not kept two year yields from continuing to press to fresh highs.

6
17
61
22,982
While the headline Philly non-manufacturing index was worse, there was an uptick in employment with prices paid climbing to its highest level since April. Not much evidence of price relief in the services sector - unwelcome news with inflation still running above target.

3
4
28
5,090
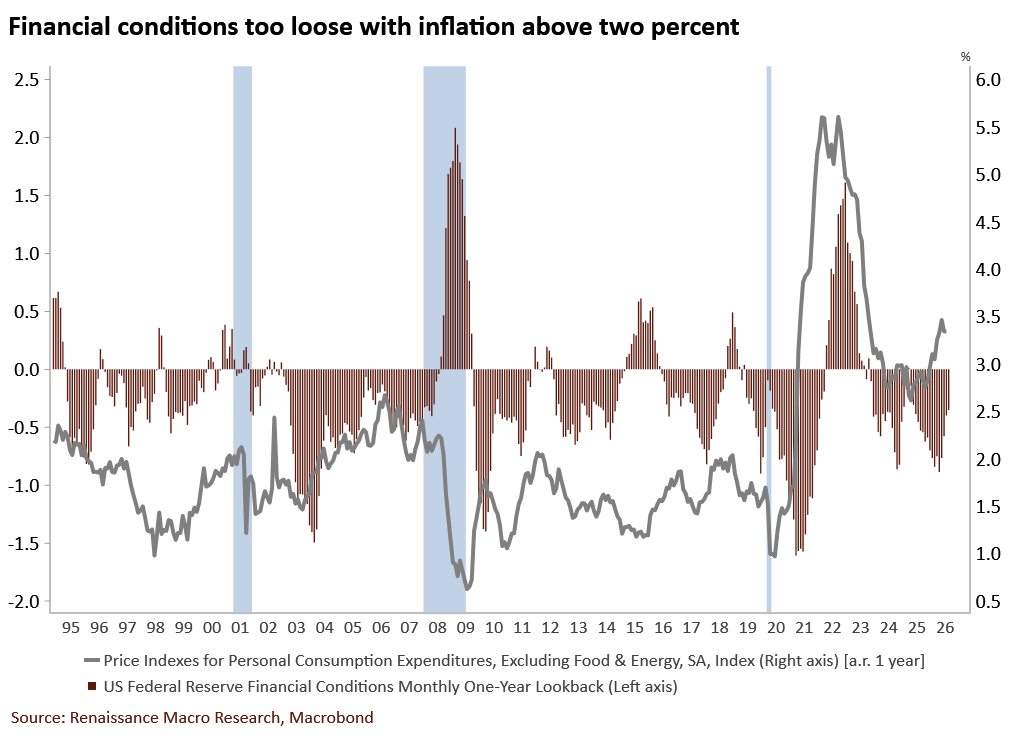
"Hard-pressed" to call financial conditions restrictive. The Fed's 1Y FCI-G stood at -0.35 in August, meaning conditions are adding that much to GDP growth over the coming year (negative = tailwind). If financial conditions are boosting GDP, it's difficult to see inflation returning to target "soon."
3
14
55
6,478
The Reality of Real Rates
Catch the full episode here: piped.video/DK3Y74QVeb8
There Is An Alternative: RenMac Off-Script
#Investing #Finance #Bonds

2
12
5,994
RenMac: Renaissance Macro Research retweeted

Consumer spending is showing signs of slowing — right as the Fed starts raising interest rates. That's going to be a double drag on the US economy. bit.ly/4xYyd6S
3
5
16
16,975
Data Center Debate: Campaign Rhetoric vs. Governing Reality
Catch the full episode here: piped.video/DK3Y74QVeb8
There Is An Alternative: RenMac Off-Script
#Politics #Economics #Policy

2
1
10
5,511
Consumer Headwinds: Why Higher Costs Are Ahead
Catch the full episode here: piped.video/DK3Y74QVeb8
There Is An Alternative: RenMac Off-Script
#Economy #ConsumerSpending

3
2
21
6,346
Fed's Interest Rate Strategy
Catch the full episode here: piped.video/DK3Y74QVeb8
There Is An Alternative: RenMac Off-Script
#FedPolicy #Economics #Finance

2
11
5,036
Why the Polls are so Close
Catch the full episode here: piped.video/DK3Y74QVeb8
There Is An Alternative: RenMac Off-Script
#USPolitics #Elections #Economy

6
5,166
Unpacking Warsh's Comments on Price Stability
Catch the full episode here: piped.video/DK3Y74QVeb8
There Is An Alternative: RenMac Off-Script
#Fed #Economy #Inflation

2
2
17
5,222